ELIGIBILITY

QUALIFYING LIFE EVENTS
Under certain circumstances, employees may be allowed to make changes to benefit elections during the plan year, if the event affects the employee, spouse, or dependent’s coverage eligibility. Any requested changes must be consistent with and on account of the qualifying event.
Examples Of Qualifying Life Events:
- Legal marital status (for example, marriage, divorce, legal separation, annulment);
- Number of eligible dependents (for example, birth, death, adoption, placement for adoption);
- Work schedule (for example, full-time, part-time);
- You, your spouse, or other covered dependent become enrolled in Part A, Part B, or Part D of Medicare
- Death of a spouse or child;
- Change in your child’s eligibility for benefits (reaching the age limit);
- Becoming eligible for Medicaid; or
- Your coverage or the coverage of your Spouse or other eligible dependent under a Medicaid plan or state Children’s Health Insurance Program (“CHIP”) is terminated as a result of loss of eligibility and you request coverage under this Plan no later than 60 days after the date the Medicaid or CHIP coverage terminates; or
- You, your spouse or other eligible dependent become eligible for a premium assistance subsidy in this Plan under a Medicaid plan or state CHIP (including any waiver or demonstration project) and you request coverage under this Plan no later than 60 days after the date you are determined to be eligible for such assistance.

HOW TO ENROLL

All team members have access to the Employee Navigator enrollment platform, where you have the ability to enroll, select or change your benefits online during the annual open enrollment period, new hire orientation, and for qualifying events. Please see your employer or broker contact prior to making changes outside of open enrollment.
- Accessible 24/7
- View all benefit plan options and your elections
- View important carrier forms and links
- Report a qualifying life event
- Make changes to beneficiary designations and more
Employee Navigator Company Identifier:
BioBridges
ENROLLMENT INSTRUCTIONS:
- Click the button below to go to your Employee Navigator enrollment portal
- Click the "Login" button located in the top right corner of your screen
- Select "Register as New User" and enter the requested information to verify your account
- Enter your Company Identifier & Pin (Last 4 digits of your SSN)
- After registering your account, click "Start Enrollment"
- You will need to complete some personal & dependent information before making your benefit elections
To get started, click on the link below to head to your Employee Navigator Enrollment Portal!

MEDICAL

Education Website | www.cigna/sage.com | (888) 806-5094
Network: Open Access Plus
How do I find an in-network doctor?
- Use the link below or visit your provider’s website at www.cigna.com under “Find a Doctor”. Select "Employer or School" and then you can search by provider/facility name or search by specialty.
- The Base Plan offers coverage at in-network providers only.
- The Buy Up Plan and Platinum Plan offer coverage at both in-network and out-of-network providers.
Did you know?
- Preventive Services are covered at 100% In-Network and copays & deductibles do not apply.
- You pay less out of pocket if you receive care from an In-Network provider.
- You do not need to designate a primary care physician or need a referral to see a Specialist.
Have questions about your benefits through Cigna?
- Call your Employee Hotline provided by Cigna: (888) 806-5094
How to access your Cigna ID Card?
- Log in to my.Cigna.com or download the myCigna app, and click "ID Cards."
- You can view your card(s) as well as any dependents' card(s), email cards directly to doctors, and save your digital ID cards in your Apple wallet.
You have 3 medical plans to choose from. Compare the different plan options in the chart below!

VIRTUAL CARE

Healthcare that's there for you when and where you need it!
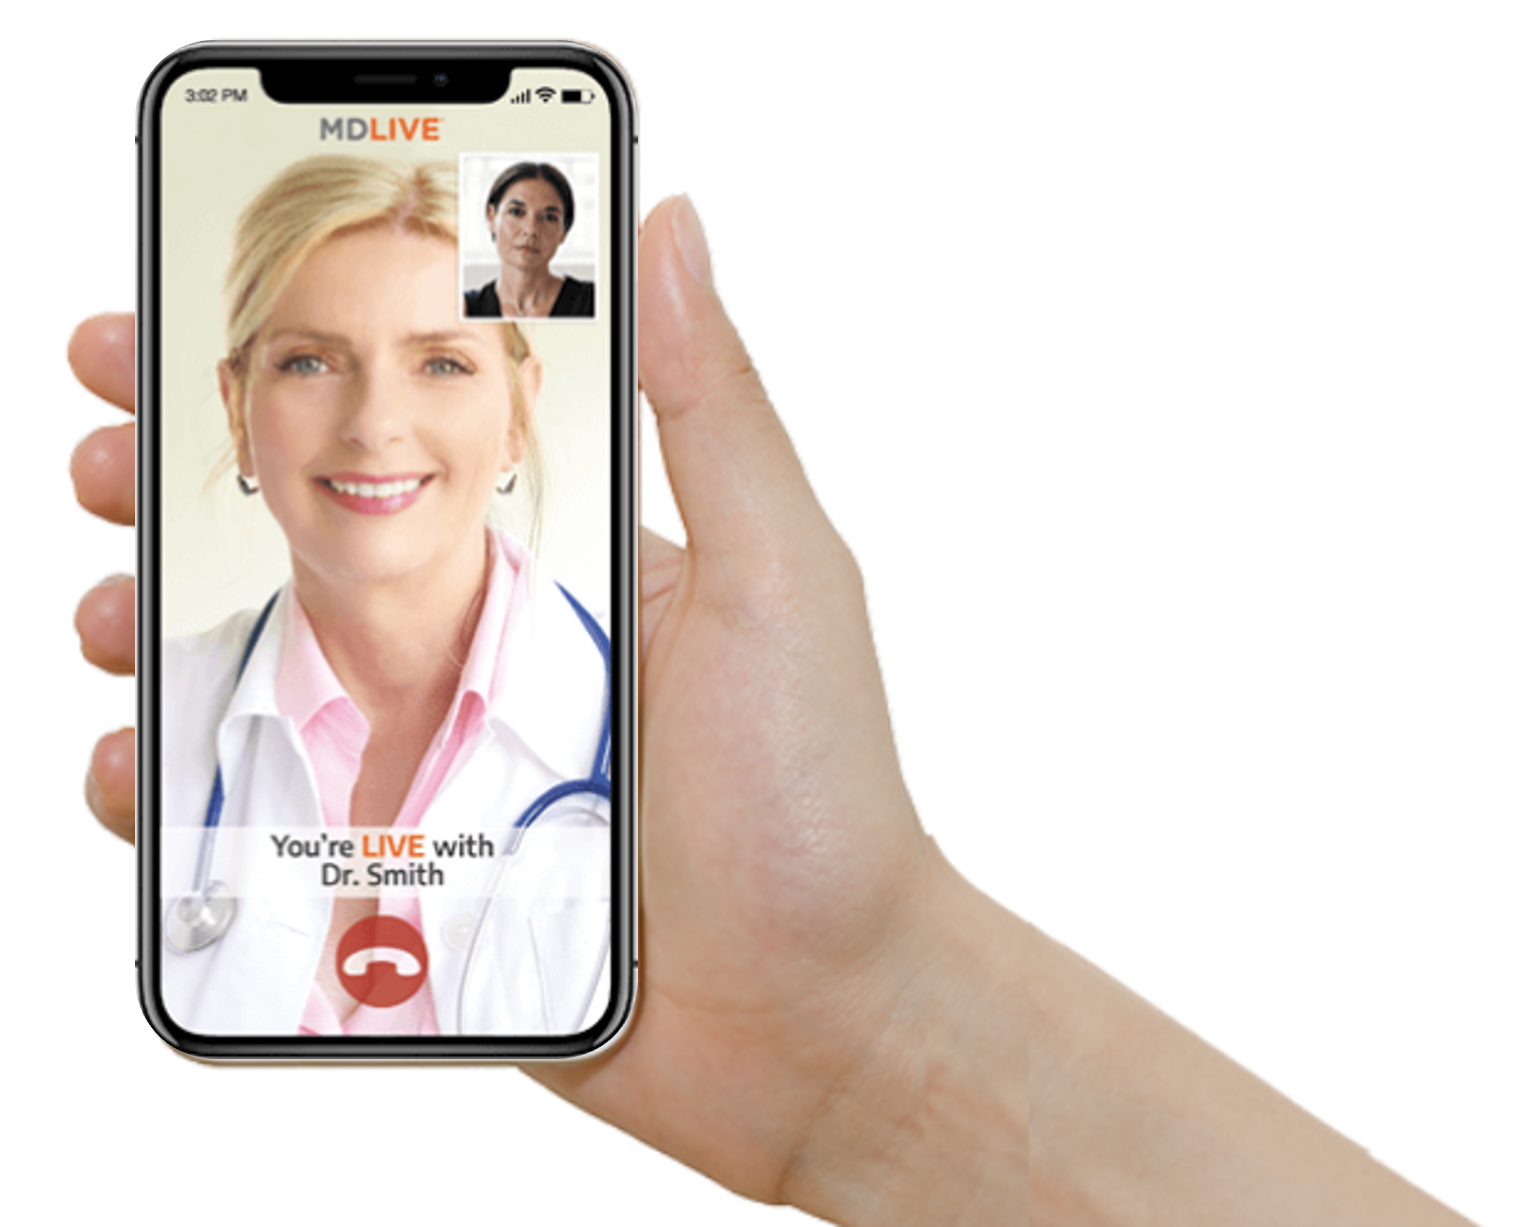
Cigna has partnered with MDLIVE to offer a comprehensive suite of convenient virtual care options — available by phone or video whenever it works for you. MDLIVE board-certified doctors, dermatologists, psychiatrists and licensed therapists have an average of over 10 years of experience, and provide personalized care for hundreds of medical and behavioral health needs.
Now you don’t have to wait — or travel — for the care you need. Connect with video or phone, whenever it’s convenient for you. Best of all, virtual care from MDLIVE board-certified doctors is available to you and your eligible dependents as part of your health benefits.

Access MDLIVE by logging into myCigna.com and clicking on “Talk to a doctor" or by calling MDLIVE at (888) 726-3171
CIGNA MOBILE APP
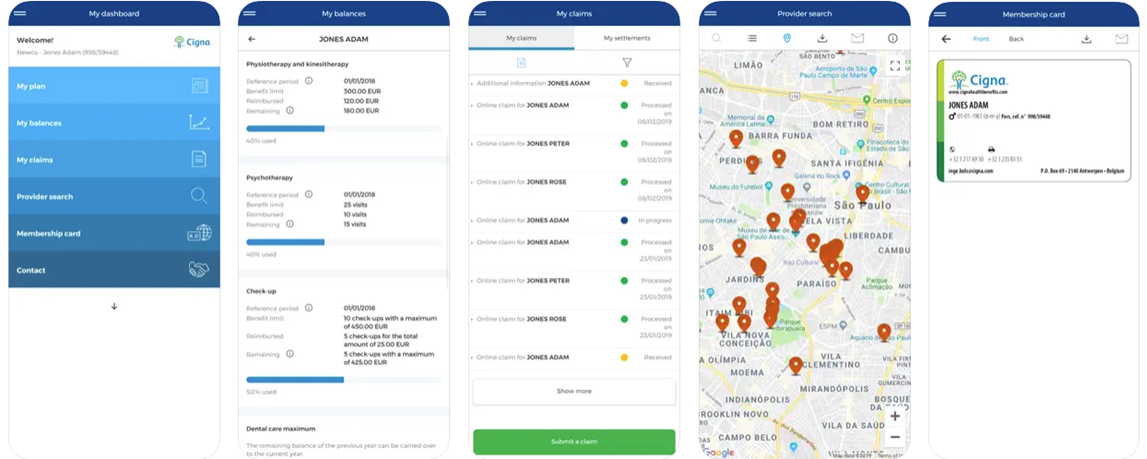
With the Cigna Health Benefits app, you can:
- Submit a claim by taking a picture of your invoice
- Download or send an electronic version of your membership card for you or a family member
- Consult past claims and track the status of pending claims
- Search for a doctor, hospital or facility, and save the search results
- Consult your benefits
- Check your remaining plan balances
- Update your personal information
- Contact us with the tap of a finger
Your health plan in your pocket


EXTRAS FROM CIGNA
As a Cigna member, you have access to a plethora of services and resources!
This is only a brief description of some of the plan benefits. For more complete details, including benefits, limitations and exclusions, please login to your Cigna member portal or learn more clicking the flyers below.
Cigna Member Portal - 
Through myCigna, our secure member website, you can access health plan information, resources and tools. The information can vary, depending on your plan.
- Review benefits, account balances, claims status and more.
- Order a replacement ID card or print a temporary card.
- View and print an Explanation of Benefits (EOB) for a claim.
Emotional Well-Being -
- Our broad support includes coverage for your emotional health, as well as tools and programs to support your general health and well-being. All of this is available to you as our health plan customer. We help you take control of your health – body and mind – whenever you need it, 24/7. You have access to three free face-to-face visits with a licensed mental health provider in our employee assistant program network. Visit your Cigna member portal at www.mycigna.com to live chat with an employee assistance program advocate, access legal services including a 30-minute no-cost consultation with a network attorney, as well as access financial services and identity theft resources.
Mental Healthcare - 
- Everyone deserves access to incredible mental health care.That’s why Headspace Care created the world’s first integrated mental health platform where coaches, therapists, and psychiatrists work as a team to coordinate the best, personalized care right from your smartphone, whenever you need it.
Talkspace - 
- Talkspace is digital space for private and convenient mental health support. With Talkspace, you are matched with a recommended, licensed provider based on your own preferences, and can receive support day and night form the convenience of your device. Users can regularly message their dedicated therapist via text, voice or video as life happens - anywhere, anytime.
Diabetes Prevention Program - 
- Omada is open to members who are considered at increased risk for developing diabetes and/or heart disease—you must meet a set of criteria in order to qualify for enrollment, such as a BMI of 25 or higher, and classic pre-diabetes risks such as elevated blood sugar, high blood pressure, high triglycerides and low HDL. The program is designed to help you reduce the risk of developing diabetes and improve your health. As part of the program, participants receive a wireless smart weight scale that is delivered directly to their home. Enrollees are able to chat one-on-one with a health coach to set goals, ask questions, and review information.
Physical Therapy Recovery - 
- RecoveryOne is a digital MSK program that provides a complete physical therapy (PT) solution conveniently delivered via a smartphone, tablet, or computer. The RecoveryOne’s online program lets members do their PT from the comfort of home, with expert support throughout their recovery.
Healthy Rewards Program - 
- Your Active&Fit Direct membership goes beyond the gym with the addition of 800+ on-demand workout videos at no additional cost. Now you can exercise from anywhere! Check out the flyer below for more information.
Identity Protection - 
- As our digital activity expands, fraud and scams increase exponentially, along with vulnerabilities that result from having sensitive personal information exposed. It’s why IdentityForce offered through Cigna will be included in your Cigna medical coverage at no additional cost for you and any child(ren) living in your household up to age 18. IdentityForce provides you with award-winning identity theft protection built to proactively monitor, alert, and help fix any identity theft compromises.
Maternity Program -
- Give your baby a healthy start with Cigna's maternity program, Cigna Healthy Babies. To support you during your pregnancy, you’ll receive information to help you learn about pregnancy and babies, 24/7 telephone support for help with questions on everything from morning sickness to maternity benefit, and support from a maternity specialist if you’re hospitalized during pregnancy or your baby is in the NICU.
Care Outside the U.S -
- When employees are traveling outside of the country – on business or pleasure – no one wants to think about a medical emergency. But when it happens, Cigna wants to make sure your employees’ care is covered. That’s why we’ve established a customer service number, specifically for individuals traveling outside the United States.
PHARMACY
Prescription drugs are a vital part of your health care coverage. If you have prescription drug coverage through Cigna, this information can help you and your doctor get the most from your prescription drug coverage. You can access more information about your pharmacy coverage by visiting www.cigna.com or logging in to your member portal at www.mycigna.com.
A formulary drug list specifies what drugs are covered under your prescription drug benefit. How much you pay out of pocket is determined by whether your drug is on the list and at what coverage level, or tier. A generic drug is often at the lower tier. See if your drug is covered by reviewing your formulary drug list using the link below!
All medical plans use the Advantage 4-tier formulary list.
- Express Scripts® Home Delivery Pharmacy: the mail order pharmacy for members with Cigna prescription drug coverage, provides safe, fast and cost-effective pharmacy services that can save you time and money. With this program, you can obtain up to a 90-day supply of long-term (or maintenance) medications through Express Scripts® Pharmacy.
- Restrictions apply to Mail Order Rx: 90-day prescriptions are only available in Walmart, Randalls, CVS, and other eligible pharmacies. Visit the myCigna app or website, or check your plan materials, to learn more.
- Accredo Specialty Pharmacy: As part of your Cigna-administered pharmacy benefits, you have access to Accredo, a Cigna specialty pharmacy. If you're using a specialty medication, their team of specialty-trained pharmacists and nurses will fill and ship your specialty medication to your home (or location of your choice). They'll also provide you with the personalized care and support you need to manage your therapy, at no extra cost.

HEALTH SAVINGS ACCOUNT (HSA)

Take charge of your health care spending with a Health Savings Account (HSA)
A Health Savings Account (HSA) is a tax-advantaged personal savings account that can be used to pay for medical, dental, vision and other qualified expenses now or later in life. To contribute to an HSA, you must be enrolled in a qualified high-deductible health plan (HDHP) and your contributions are limited annually.
How It Works
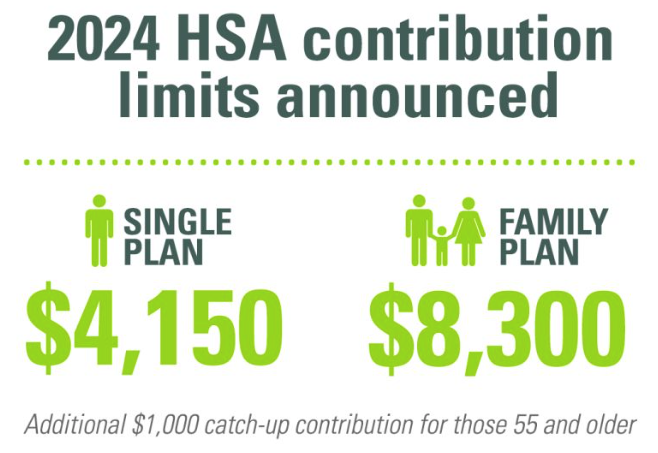
- For 2026, Participants can make an annual election of up to $4,400 for self only HDHP coverage or $8,750 for family High Deductible Health Plan (HDHP) medical coverage.
- Your employer deducts per pay-period the amount you elect on a tax-free basis. You can also contribute post-tax contributions (up to the maximum allowed) and recognize the same tax savings by claiming the deduction when filing your annual taxes.
- Eligible healthcare purchases can be made tax-free when you use your HSA. Purchases can be made directly from your HSA account, either by using your debit card, online bill-pay, or check – or you can pay out-of-pocket and then reimburse yourself from your HSA.
- The interest on HSA funds grows on a tax-free basis, and interest earned on an HSA is not considered taxable income when the funds are used for eligible medical expenses.
Why Participate? HSAs save you money!
- The contributions you make to an HSA are deducted from your paycheck on a pre-tax basis – before federal income, social security, and most state taxes.
- The end results of your HSA contributions is a lower taxable income, and a tax advantaged vehicle to pay for out-of-pocket healthcare expenses and prepare for your healthcare costs in retirement.
- While your funds can be used to pay for immediate healthcare expenses tax-free, you can also save the money for healthcare expenses later in life.
- You can continue to contribute year after year and withdrawals (provided you are enrolled in an HDHP) can be made at any point in time.
- Whether you withdraw the money tomorrow, five years from now, or in retirement, funds used for qualified healthcare expenses are always tax-free.
Who's Covered?
- An HSA covers qualified out-of-pocket expenses for you, your spouse, your tax dependents, even if they are not covered under an HDHP.

FLEXIBLE SPENDINGS ACCOUNT (FSA)

A Flexible Spending Account is an indispensable part of your overall benefits program. An FSA is an account your employer sets up so you can pay for a variety of healthcare needs, like insurance co-pays, deductibles, dental, vision, pharmacy and even some over-the-counter medication costs, reimbursed under the Health FSA. But here’s the best part: Your FSA is funded entirely by your pre-tax income. This means you can save money and offset rising healthcare costs at the same time. That’s like found money to spend on all those everyday items you and your family need!
Why Participate?
- FSAs save you money! The contributions you make to an FSA are deducted from your pay check on a pre-tax basis – before federal income, social security, and most state taxes. The end results of your FSA contributions is a lower taxable income, and a tax advantaged vehicle to pay for out-of-pocket healthcare expenses.
- FSAs help you:
- Reduce taxable income – Contributions lower your reported annual income, resulting in lower taxable wages.
- Save on healthcare expenses – Using pre-tax funds to pay out of pocket expenses can save you hundreds!
- Offset rising healthcare costs and individual financial responsibility.
Maximum Annual Contribution
- For the 2026 plan year, individuals can contribute a maximum of $3,400.
Eligible Expenses
- A full list of qualified FSA expenses can be found in IRS Publication 502 at www.irs.gov.
- You can learn more about FSA qualified expenses and also make purchases by visiting the FSA Store at www.fsastore.com.
DENTAL

Member Services | (888) 899-3734 | www.deltadental.com
NETWORK: Delta Dental PPO Plus Premier Network
How do I find a Delta Dental In-Network Dentist?
- Click the link below or visit www.deltadentalid.com and select “Find a Dentist” wherever you are located or you may contact customer service at (208) 489-3580.
- You have the freedom to select the dentist of your choice; however, when you visit a participating in-network dentist, you will have lower out-of-pocket costs, no balance billing, and claims will be submitted by your dentist on your behalf.
Pre-treatment Estimate
- If your dental care is extensive and you want to plan ahead for the cost, you can ask your dentist to submit a pre-treatment estimate. While it is not a guarantee of payment, a pre-treatment estimate can help you predict your out-of-pocket costs.
Dental Health Education and Online Risk Assessment Tool
- Delta Dental provides an Oral Health and Wellness site that includes an interactive risk assessment tool that will assess your risk of dental disease. Any member can access a vast array of wellness topics, articles and the interactive risk assessment. Click the link below to learn more.
Looking for more details about how items are covered? Click on the link below to view the formal Benefit Summary

VISION

Principal Customer Service | (800) 247-4695 | www.principal.com
Network: VSP Choice
How do I find an In-Network Provider?
- Use the link below or visit www.vsp.com under "Find a Doctor" then you can search vision providers by location, office, or search for a specific doctor.
Did You Know?
- Eyes can give doctors a clear picture of overall wellness. That’s why vision care—and vision benefits—can help employees stay healthy.
- A comprehensive eye exam can detect early signs of serious health problems, such as diabetes, heart disease, high blood pressure, high cholesterol, glaucoma and cataracts.
Looking for more details about how items are covered? Click on the link below to view the formal Vision Plan Summary.

SURVIVOR BENEFITS
Principal Customer Service | (800) 247-4695 | www.principal.com
i
Basic Life and Accidental Death & Dismemberment (AD&D)
i
Life insurance is an important part of your financial security as it helps protect your family from financial risk and sudden loss of income in the event of your death. AD&D (Accidental Death & Dismemberment) insurance is equal to your Life benefit in the event of your death being a result of an accident, and may pay benefits for particular injuries sustained.
i
- Basic Life / AD&D insurance is a company paid benefit, provided to you at no cost.
- The plan pays a flat benefit of $50,000.
- Keep in mind, your life insurance benefit amount will reduce to 35% of the original amount at age 65 and an additional 15% of the original amount at age 70.
i
Looking for more details about how items are covered? Click on the link below to view the formal Basic Life and AD&D Plan Summary.
i
Principal Customer Service | (800) 247-4695 | www.principal.com
i
Voluntary Life and AD&D Insurance
i
In addition to your employer provided Basic Life insurance coverage, you have the opportunity to enroll in Voluntary Life and AD&D Insurance. Coverage is also available for your spouse and/or child dependents, however, It is required that you elect coverage for yourself in order to elect coverage for your dependents.
i
If you have previously elected Voluntary Life but are under the Guarantee Issue (GI) amount, you may increase your amount up to the Guarantee Issue (GI) without Evidence of Insurability (EOI) at Open Enrollment. If you previously waived Voluntary Life you will need to submit Evidence of Insurability (EOI).
i
How does it work?
- You choose the amount of coverage that’s right for you, and you keep coverage for a set period of time, or “term.” If you die during that term, the money can help your family pay for basic living expenses, final arrangements, tuition and more. AD&D Insurance is also available, which pays a benefit if you survive an accident but have certain serious injuries. It pays an additional amount if you die from a covered accident.
i
Who can get Voluntary Term Life Coverage?
- Employee: Choose from $10,000 to $300,000 in $10,000 increments. If you're below the age of 70, you can get a guaranteed issue (GI) of up to $100,000. If you're 70 or older, your GI is up to $10,000. This is the amount of coverage you can qualify for with no medical underwriting.
- Spouse: Get up to $100,000 of coverage in $5,000 increments. Spouse coverage cannot exceed 100% of the coverage amount you purchase for yourself. Your spouse can get a GI of up to $25,000 (below 70) or $10,000 (70 and above) with no medical underwriting, if eligible.
- Children: Get either $5,000 or $10,000 worth of coverage if eligible. One policy covers all of your children until their 26th birthday. The maximum benefit for children live birth to 14 days is $1,000.
i
Guaranteed Issue (GI) and Evidence of Insurability (EOI)
- When you are first eligible (at hire) for Voluntary Life and AD&D, you may purchase up to the Guaranteed Issue (GI) for yourself and your spouse without providing proof of good health (EOI).
- Any amount elected over the GI will require EOI. If you elect optional life coverage and are required to complete an EOI, it is your responsibility to complete the EOI and send to the provider. In addition, your spouse will need to provide EOI to be eligible for coverage amounts over GI, or if coverage is requested at a later date.
i
Looking for more details about how items are covered? Click on the link below to view the formal Voluntary Life and AD&D Plan Summary.
i
INCOME PROTECTION
Principal Customer Service | (800) 247-4695 | www.principal.com
i
Short-Term Disability Insurance
i
Everyday illnesses or injuries can interfere with your ability to work. Even a few weeks away from work can make it difficult to manage household costs. This employer-paid Short Term Disability coverage provides financial protection for you by paying a portion of your income, so you can focus on getting better and worry less about keeping up with your bills. This benefit is provided to you at no cost!
i
- Elimination Period - Benefits begin on the 15th day of an injury or illness.
- Benefit Duration - Payments may last up to 24 weeks (You must be sick or disabled for the duration of the waiting period before you can receive a benefit payment).
- Coverage Amount - Covers 60% of your weekly income, up to a maximum benefit of $600 per week.
i
What does this mean to you?
- If you are out of work for 14 days due to an illness or accident, you can begin receiving disability benefits on day 15. This is a cash benefit of 60% of your weekly salary to a max of $600 when you are out of work. You are able to receive this benefit for up to 2 weeks. A partial cash benefit is available if you can only do part of your job or work part-time.
i
Looking for more details about how items are covered? Click on the link below to view the formal Short-Term Disability Plan Summary.
i
Principal Customer Service | (800) 247-4695 | www.principal.com
i
Long-Term Disability Insurance
i
This employer-paid coverage pays a monthly benefit if you have a covered illness or injury and you can't work for a few months - or even longer! You're generally considered disabled if you're unable to do important parts of your job - and your income suffers as a result. This benefit is provided to you at no cost!
i
- Elimination Period- Benefits begin following 180 days after an injury or illness.
- Benefit Duration - Payments may last up to Social Security Normal Retirement Age (SSNRA)
- (You must be sick or disabled for the duration of the waiting period before you can receive a benefit payment).
- Coverage Amount - Covers 50% of your monthly income, up to a maximum benefit of $5,000 per month.
- 3/12 Pre-existing Condition: If you have a medical condition that begins before your coverage takes effect, and you receive treatment for this condition within the three months leading up to your coverage start date, you may not be eligible for benefits for that condition until you have been covered by the plan for 12 months.
i
What does this mean to you?
- If you are still unable to work after your Short Term benefit expires, you will have the opportunity to receive a Long Term Disability cash benefit. Starting after the 180th day you are out of work due to an illness or injury, you will receive 50% of your monthly salary to a max of $5,000 per month. You are able to receive these benefits for as long as you remain disabled or reach Social Security Normal Retirement Age (SSNRA).
i
Looking for more details about how items are covered? Click on the link below to view the formal Long-Term Disability Plan Summary.
i
REIMBURSEMENT
Accident Insurance
A serious injury can cost you a lot of money – not only in medical bills but in things like income from lost work hours. Accident insurance is a robust shield against the unpredictable, safeguarding you against the financial fallout of unforeseen injuries. It pays a set benefit amount based on the type of injury you have and the type of treatment you need, ensuring that whether you face minor bruises or major medical emergencies, you're covered. Here's what accident insurance typically covers:
- Comprehensive Coverage: From fractures and dislocations to burns and concussions, accident insurance has you covered for a wide range of injuries.
- Medical Expenses: It helps offset expenses related to ambulance rides, hospital admissions, surgeries, therapy, and other necessary treatments.
- Income Protection: Should an injury result in lost work hours, accident insurance provides a financial safety net to help bridge the gap until you're back on your feet.
With accident insurance in your corner, you can face life's uncertainties with confidence, knowing that you're financially protected against the unexpected. However, it's important to note that accident insurance typically excludes coverage for routine check-ups or hospitalization due to illness. Additionally, injuries sustained prior to purchasing the accident insurance plan are not covered. For a detailed breakdown of benefits and coverage, refer to the plan summary provided below.
Voluntary Critical Illness Insurance
Facing a critical illness can bring not only physical strain but also financial burdens due to medical expenses and potential loss of income. Critical illness insurance serves as a robust safety net in such challenging times, offering financial protection against the unforeseen. In the event of a critical illness diagnosis, this insurance provides a lump-sum payment to the insured individual, enabling them to cover various expenses, including medical treatments, mortgage payments, and daily living expenses. Here's what critical illness insurance typically covers:
- Coverage for Various Conditions: Critical illness insurance typically covers a wide range of serious medical conditions, including cancer, heart attacks, strokes, organ transplants, and more. Visit your plan summary below to learn how different illnesses are covered.
- Financial Assistance: The policy provides a lump-sum payment upon diagnosis of a covered critical illness, allowing individuals to use the funds as needed for medical expenses, household bills, or other financial obligations.
- Flexibility and Peace of Mind: With critical illness insurance, employees gain peace of mind knowing they have financial protection in place, regardless of the specific illness they may face. This flexibility ensures that they can focus on their health and well-being without worrying about the financial consequences of a critical illness.
While critical illness insurance provides invaluable protection against serious medical conditions, it's essential to note that the plan typically excludes pre-existing conditions diagnosed before the policy's effective date, as well as certain illnesses not specified in the plan. Additionally, routine check-ups and hospitalization due to non-critical illnesses are typically not covered. For a comprehensive understanding of the benefits and limitations of your specific plan, be sure to review the plan summary provided below.
Hospital Indemnity Insurance
Even if you have medical insurance, a trip to the hospital can leave you with significant unexpected expenses. Hospital indemnity insurance is a valuable addition to your benefits package, providing financial protection in the event of hospitalization due to illness or injury. This insurance offers a fixed daily benefit amount for each day you're hospitalized, helping offset expenses not covered by your primary health insurance, such as deductibles, copayments, and other out-of-pocket costs. It serves as a financial safety net, ensuring that you can focus on your recovery without worrying about the financial impact of a hospital stay. Here's what hospital indemnity insurance typically includes:
- Daily Hospitalization Benefit: You receive a fixed cash benefit for each day spent in the hospital, providing financial assistance to cover various expenses incurred during your stay. You can receive benefits when you’re admitted to the hospital for a covered accident, illness, or childbirth. See the full list in the plan summary below.
- Flexibility in Use: The benefit can be used at your discretion to cover costs like deductibles, copayments, transportation, and even household bills while you're unable to work.
While hospital indemnity insurance offers valuable financial support during hospitalization, it's important to note that it typically excludes coverage for pre-existing conditions and certain elective procedures. Additionally, benefits may not be payable for hospital stays due to specific causes, so be sure to review the plan summary below for more information on coverage details and limitations. Your understanding of the plan specifics will empower you to make informed decisions about your healthcare coverage.


EMPLOYEE ASSISTANCE PROGRAM (EAP)

EAP Member Services | (800) 450-1327 | www.member.magellanhealthcare.com
i
Find professional support when you need it for challenging life events.
Your Mental Health and Wellbeing is very important to Round Rock Christian Academy, that's why through your Employee Assistance Program, you have access to many helpful services that address personal life challenges and improve workplace productivity and performance. We are proud to offer our Employee Assistance Program (EAP) in partnership with Magellan Healthcare.
i
- You and your family members can utilize EAP services and have a resource for life’s everyday and not so everyday challenges — no copays or deductibles needed.
- You automatically receive EAP services with your Principal life and disability coverage.
- Provided by Magellan Healthcare, EAP services include 24/7 phone consultation with licensed mental health professionals, online information and services, referrals to community resources and more.
ii
EAP services available to you and your family:
- In-person or virtual counseling
- Legal, financial, and identity theft protection services
- Work-life web services
i
Review plan details and contact information in the Employee Assistance Program Flyer provided in the link below.
i

MENTAL HEALTH: ADDITIONAL RESOURCES
Call 911 if you or someone you know is in immediate danger or go to the nearest emergency room.
988 Suicide & Crisis Lifeline
- Dial 988 to be connected with 24/7/365 emotional support.
- Free, confidential crisis counseling, including appropriate follow-up services, is available no matter where you live in the United States.
War Vet Call Center
- Veterans and their families call 877-WAR-VETS (877-927-8387) to talk about their military experience and/or readjustment to civilian life.