ELIGIBILITY

QUALIFYING LIFE EVENTS
Under certain circumstances, employees may be allowed to make changes to benefit elections during the plan year, if the event affects the employee, spouse, or dependent’s coverage eligibility. Any requested changes must be consistent with and on account of the qualifying event.
Examples Of Qualifying Events:
- Legal marital status (for example, marriage, divorce, legal separation, annulment);
- Number of eligible dependents (for example, birth, death, adoption, placement for adoption);
- Work schedule (for example, full-time, part-time);
- You, your spouse, or other covered dependent become enrolled in Part A, Part B, or Part D of Medicare
- Death of a spouse or child;
- Change in your child’s eligibility for benefits (reaching the age limit);
- Becoming eligible for Medicaid; or
- Your coverage or the coverage of your Spouse or other eligible dependent under a Medicaid plan or state Children’s Health Insurance Program (“CHIP”) is terminated as a result of loss of eligibility and you request coverage under this Plan no later than 60 days after the date the Medicaid or CHIP coverage terminates; or
- You, your spouse or other eligible dependent become eligible for a premium assistance subsidy in this Plan under a Medicaid plan or state CHIP (including any waiver or demonstration project) and you request coverage under this Plan no later than 60 days after the date you are determined to be eligible for such assistance.

HOW TO ENROLL

Using your desktop or mobile device, you have access to our online benefits enrollment platform 24/7. In your Workday Portal you can:
- View and select benefits for yourself and dependents
- View per-pay-period amounts
- Submit qualifying life events
- Add and edit beneficiaries and dependents
How to Enroll
- Login to Workday
- Click the inbox in the top right
- In your inbox there should be a task called "Verify your Personal Contact Information"
- Once you have completed that task another one will populate in your inbox called "Open Enrollment Change"
- Click the blue "Let's get started" button in the task
- Verify your personal information and dependent information
- Make Benefit Elections
- Review your elections and Click “Review and Submit”, double check all of your selections and click the I accept box
- Submit your elections


Customer Service | (866) 747-0048 | cobra_kyoperations@uhc.com
The Consolidated Omnibus Budget Reconciliation Act (COBRA) gives workers and their families the right to continue their existing group health plan coverage for a limited period of time when they would otherwise lose their coverage through a voluntary or involuntary job loss, a reduction in work hours, death, divorce, or other events.
The cost for coverage under COBRA is usually higher than the cost for employees under a group plan.
- COBRA participants usually pay 100% of the coverage, plus a 2% administrative fee.
- For employees who choose not to re-enroll in benefits during Open Enrollment, the loss of insurance coverage is not a qualifying event for COBRA.
Cobra Qualifying Events
The following are qualifying events for covered employees if they cause the covered employee to lose coverage:
- Termination of the employee's employment for any reason other than gross misconduct.
- Reduction in the number of hours of employment.
The following are qualifying events for the spouse and dependent child of a covered employee if they cause the spouse or dependent child to lose coverage:
- Termination of the covered employee's employment for any reason other than gross misconduct.
- Reduction in the hours worked by the covered employee.
- Covered employee becomes entitled to Medicare.
- Divorce or legal separation of the spouse from the covered employee.
- Death of the covered employee.
In addition to the above, the following is a qualifying event for a dependent child of a covered employee if it causes the child to lose coverage:
- Loss of dependent child status under the plan rules.
- Under the Patient Protection and Affordable Care Act, plans that offer coverage to children on their parents' plan must make the coverage available until the adult child reaches the age of 26.
MEDICAL

Member Services | (866) 844-4864 | www.myuhc.com | Group #0942378
Network: Choice Plus PPO
How do I find an In-Network Doctor?
- Use the link below or visit your provider’s website at www.uhc.com and select “Find a Doctor”.
- Both medical plans offer coverage at both in-network and out-of-network providers. The doctors and facilities in the network have agreed to provide services at a discount — so visiting an out-of-network provider could end up costing you more for care.
Did You Know?
- Preventive Services are covered at 100% In-Network and copays & deductibles do not apply. This means your routine annual physical, well-child visits, certain immunizations, and other preventive tests may be provided at no cost to you.
- You pay less out of pocket if you receive care from a Designated In-Network provider.
- You do not need a referral to see a Specialist.
You have 3 medical plans to choose from. Compare the options in the charts below!

Summary of Benefits and Coverage (SBC)
Looking for more details about how items are covered? Please refer to the formal Summary of Benefits and Coverage (SBC) below. There is one for each plan!
PHARMACY

OptumRx Customer Service | 800-356-3477 | www.optumrx.com
On your prescription benefits, you may see the name OptumRx®, which is UnitedHealthcare’s pharmacy service provider. OptumRx may be included in your health plan benefits because it offers members coverage through a large network of retail chain and independent pharmacies, as well as through its mail service pharmacy known as OptumRx Home Delivery and the Optum Specialty Pharmacy.
Pharmacy through the UHC Mobile App
UnitedHealthcare members with health plans through an employer may use the UnitedHealthcare app to help manage their medications. You can use the app to:
- Set up and refill home delivery orders
- Track your prescription history
- Find network pharmacies
- Compare medication prices
Tips that May Help Save Money on Medications!
- Check your Prescription Drug List (PDL) often to stay ahead of changes in coverage
- Talk to your doctor about lower-cost alternatives if a medication is too expensive
- Sign in to your health plan account to find network pharmacies
- Check out Pharmacy FAQs

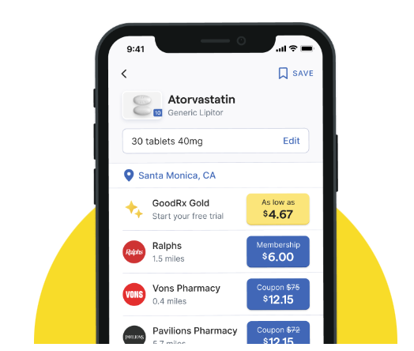
Save up to 80% on your prescriptions with the free GoodRx Mobile App!
How does GoodRx work?
- Prescription drug prices are not regulated. The cost of a prescription may differ by more than $100 between pharmacies across the street from each other! GoodRx gathers current prices and discounts to help you find the lowest cost pharmacy for your prescriptions
How do I find discounts for my drug?
- It’s easy. Just visit www.goodrx.com, type in your drug’s name in the search field, and click the “Find the Lowest Price” button.
What are GoodRx coupons?
- GoodRx coupons will help you pay less than the cash price for your prescription. They’re free to use and are accepted at virtually every U.S. pharmacy.
- Your pharmacist will know how to enter the codes on the coupon to pull up the lowest discount available.
VIRTUAL VISITS

A convenient and faster way to get care
- Doctors can treat a wide range of health conditions - including many of the same conditions as an emergency room (ER) or urgent care - and may even prescribe medications, if needed.
- Consider Virtual Visits for these common conditions:,Allergies, bronchitis, eye infections, flu, headaches/migraines, rashes, sore throats, stomachaches, and more.
Virtual Visits Cost
- Gold/Silver Plan: $0 Copay
- HDHP Plan: $0 Copay, Ded. Waived
Get Started
- Sign in at myuhc.com/virtualvisits
- Call 1 (855) 615-8335
- Download the UnitedHealthcare app
UHC APP
Get your health info, anytime
When you want to easily access your health information anywhere you go, the UnitedHealthcare app is your go-to. Download it today to get instant access to your health plan details.
Find care
- Find network care options for doctors, clinics and hospitals in your area.
- Talk to a doctor by video 24/7.
- See reviews and ratings for doctors.
Manage your health plan details
- Generate and share digital health plan ID cards.
- View claims and account balances.
- Manage prescription drugs and refills.
Stay on top of costs
- Estimate the costs of common procedures.
- View your copay, annual deductible and out-of-pocket expenses.
- View your Health Savings Account, if applicable.


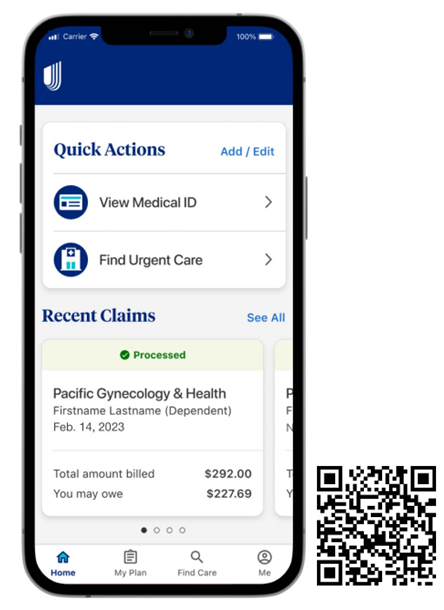


As a UHC member, you have access to a plethora of services and resources!
This is only a brief description of some of the plan benefits. For more complete details, including benefits, limitations and exclusions, please login to your UHC Member portal.
MYUHC member portal
Through UHC our secure member website, you can access health plan information, resources and tools. The information can vary depending on your plan.
- Review Benefits, account balances, claims status and more.
- House Medical/Dental/Vision ID cards or request new ones be delivered
- Find a provider, dentist, or vision provider
- Get estimates for treatments and procedures
- Speak with an online health coach
MYUHC Mobile
MYUHC Mobile makes it easy for you to access your information while on the go. You can view coverage details, health and wellness information, check claims status, and access member ID cards.
Valuable Member Programs
As a UHC member you have access to a range of programs that can help you get and stay healthy
- 24/7 Virtual Visits - you can connect to a provider by phone or video1 through myuhc.com or the UnitedHealthcare appProviders can treat a wide range of health conditions — including many of the same conditions as an emergency room (ER) or urgent care — and may even prescribe medications,2 if needed. With a UnitedHealthcare plan, your cost for a 24/7 Virtual Visit is usually $54 or less.
 - With One Pass Select™, we’re on a mission to make fitness engaging for everyone. One Pass Select can help you reach your fitness goals, while finding new passions along the way. Find a routine that’s right for you whether you work out at home or at the gym. Choose a membership tier that fits your lifestyle and provides everything you need for whole body health in one easy, affordable plan. As of January 1, 2025, you and your eligible family members (18+) can get started with One Pass Select when you activate UnitedHealthcare Rewards. Plus, you can use your earnings to help pay for your One Pass Select membership.
 - Real Appeal on Rally Coach™ is a proven weight management program designed to help you get healthier and stay healthier. It’s available to you and eligible family members at no additional cost as part of your benefits. Set achievable nutrition, exercise and weight management goals that keep you motivated to create lasting change. Track your progress from your daily dashboard, too. Make the most of tools and resources like weight and food scales, a portion plate and more. Your Success Kit is delivered after you attend your first live group session.
 - Good news — your health plan comes with a way to earn up to $300. UnitedHealthcare Rewards is included in your health plan at no additional cost. With UHC Rewards, a variety of actions — including things you may already be doing, like tracking your steps or sleep — lead to rewards. The activities you go for are up to you, and the same goes for ways to spend your earnings.
- UHC Vision - Your UnitedHealthcare Vision plan offers a selection of popular contact lenses to help you get the most out of your coverage. If you choose contact lenses that are not included in this list, you may use your contact lens allowance toward your purchase. Your eye doctor can help determine which contact lenses are best for you.

HEALTH SAVINGS ACCOUNT (HSA)

Member Services | (800) 357-6246 | www.HSABank.com
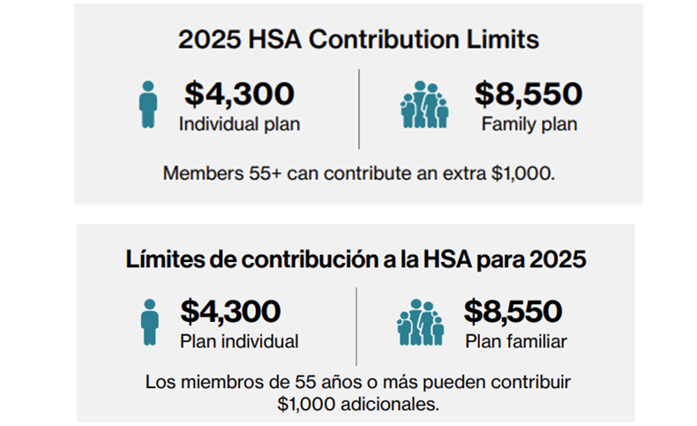
A Health Savings Account (HSA) is a tax-advantaged personal savings account that can be used to pay for medical, dental, vision and other qualified expenses now or later in life. To contribute to an HSA, you must be enrolled in the HDHP/HSA Plan and your contributions are limited annually.
City of Cedar Park contributes $600 (Employee) / $1,200 (Family) annually to your HSA!
How It Works
- For 2027, Participants can make contributions of up to $4,500 for self only HDHP coverage or $9,000 for family High-Deductible Health Plan (HDHP) medical coverage. This includes both your contributions and the contributions made by City of Cedar Park.
- Your employer deducts per pay-period the amount you elect on a tax-free basis. You can also contribute post-tax contributions (up to the maximum allowed) and recognize the same tax savings by claiming the deduction when filing your annual taxes.
- Eligible healthcare purchases can be made tax-free when you use your HSA. Purchases can be made directly from your HSA account, either by using your debit card, online bill-pay, or check – or you can pay out-of-pocket and then reimburse yourself from your HSA.
- The interest on HSA funds grows on a tax-free basis, and interest earned on an HSA is not considered taxable income when the funds are used for eligible medical expenses.
Why Participate? HSAs save you money!
- The contributions you make to an HSA are deducted from your paycheck on a pre-tax basis – before federal income, social security, and most state taxes.
- The end results of your HSA contributions is a lower taxable income, and a tax advantaged vehicle to pay for out-of-pocket healthcare expenses and prepare for your healthcare costs in retirement.
- While your funds can be used to pay for immediate healthcare expenses tax-free, you can also save the money for healthcare expenses later in life.
- You can continue to contribute year after year and withdrawals (provided you are enrolled in an HDHP) can be made at any point in time.
- Whether you withdraw the money tomorrow, five years from now, or in retirement, funds used for qualified healthcare expenses are always tax-free.
Who's Covered?
- An HSA covers qualified out-of-pocket expenses for you, your spouse, your tax dependents, even if they are not covered under an HDHP.
FLEXIBLE SPENDINGS ACCOUNT (FSA)

Member Services | (800) 422-4661 | www.tasconline.com
An FSA is an account your employer sets up so you can pay for a variety of healthcare needs, like insurance co-pays, deductibles, dental, vision, pharmacy and even some over-the-counter medication costs, reimbursed under the Health FSA. This would not be an option for employees enrolling the HDHP/HSA Plan who want to open a Health Savings Account (HSA).
Why Participate?
- Reduce taxable income – FSA Contributions are deducted from your paycheck on a pre-tax basis, so they lower your reported annual income, resulting in lower taxable wages.
- Save on healthcare expenses – Using pre-tax funds to pay out of pocket expenses can save you hundreds!
- Offset rising healthcare costs and individual financial responsibility.
Maximum Annual Contribution
- For the 2027 plan year, the Healthcare FSA contribution limit is $3,500 per employee.
Use-It-Or-Lose-It
- FSA account holders must use the entirety of their tax-free funds before the end of each plan year or forfeit any remaining FSA funds.
Eligible Expenses
- A full list of qualified FSA expenses can be found in IRS Publication 502 at www.irs.gov.
- You can learn more about FSA qualified expenses and also make purchases by visiting the FSA Store at www.fsastore.com.
DENTAL

Member Services | (888) 899-3734 | www.deltadental.com
NETWORK: Delta Dental PPO Plus Premier Network
How do I find a Delta Dental In-Network Dentist?
- Click the link below or visit www.deltadentalid.com and select “Find a Dentist” wherever you are located or you may contact customer service at (208) 489-3580.
- You have the freedom to select the dentist of your choice; however, when you visit a participating in-network dentist, you will have lower out-of-pocket costs, no balance billing, and claims will be submitted by your dentist on your behalf.
Pre-treatment Estimate
- If your dental care is extensive and you want to plan ahead for the cost, you can ask your dentist to submit a pre-treatment estimate. While it is not a guarantee of payment, a pre-treatment estimate can help you predict your out-of-pocket costs.
Dental Health Education and Online Risk Assessment Tool
- Delta Dental provides an Oral Health and Wellness site that includes an interactive risk assessment tool that will assess your risk of dental disease. Any member can access a vast array of wellness topics, articles and the interactive risk assessment. Click the link below to learn more.
Looking for more details about how items are covered? Click on the link below to view the formal Benefit Summary

VISION

EyeMed Vision Care® is a registered trademark of EyeMed Vision Care, LLC
Member Services | (866) 800-5457 | www.EyeMed.com
Network: EyeMed Insight Network
How do I find an In-Network Provider?
- Use the helpful link below or visit www.eyemed.com under the "Member & Consumers" tab, then select "Find An Eye Doctor." Your vision plan utilizes the Insight Network.
- Staying in-network helps you save money on eye exams, frames and lenses. Visiting a PLUS Provider is designed to help you save even more. And since PLUS Providers are already in-network, the additional perks are built right into your vision benefits. No promo codes, no coupons, no paperwork. The same vision benefits, plus a little more savings.
Did You Know?
- Eyes can give doctors a clear picture of overall wellness. That’s why vision care—and vision benefits—can help employees stay healthy. A comprehensive eye exam can detect early signs of serious health problems, such as diabetes, heart disease, high blood pressure, high cholesterol, glaucoma and cataracts

Looking for more details about how items are covered? Click on the link below to view the formal Benefit Summary.

SURVIVOR BENEFIT

Member Services | (833) 310-8260 | www.SecurianFinancial.com
Basic Life and Accidental Death & Dismemberment (AD&D)
Life insurance is an important part of your financial security as it helps protect your family from financial risk and sudden loss of income in the event of your death. AD&D (Accidental Death & Dismemberment) insurance is equal to your Life benefit in the event of your death being a result of an accident and may pay benefits for particular injuries sustained.
City of Cedar Park pays for Group Life and Voluntary Life plans are provided through Securian Financial Group. City of Cedar Park provides you with the following company-paid Life/AD&D insurance plans:
- For employees, you are covered for 2 times your annual salary, up to $300,000 for both Life and AD&D. This benefit amount reduces to 65% of the original amount at age 70, to 40% at age 75, and to 25% at age 80
Voluntary Life
In addition to your employer provided Basic Life insurance coverage, you have the opportunity to enroll in Voluntary Life. Coverage is also available for your spouse and/or child dependents, however, It is required that you elect coverage for yourself in order to elect coverage for your dependents.

Voluntary AD&D
In addition to your employer provided Basic Life insurance coverage, you have the opportunity to enroll in AD&D Insurance. Coverage is also available for your spouse and/or child dependents, however, It is required that you elect coverage for yourself in order to elect coverage for your dependents.

Life insurance portability and conversion options are features that allow policyholders to maintain some level of insurance coverage when they might otherwise lose it or wish to change the type of coverage they have.
Portability
- Refers to the ability of an individual to transfer their group life insurance coverage from one employer to another or from a group policy to an individual policy without undergoing new underwriting or providing evidence of insurability.
- This is commonly associated with group term life insurance provided by employers. If you (the employee) leave your job or retire, you may not want to lose your life insurance coverage, especially if there are ongoing health issues. Advantages of porting coverage are that it allows continuity of coverage and there is no need for medical examination or evidence of insurability.
- The application and check for the initial premium must be received within 31 days after Life Insurance terminates or 15 days from the date the Employer signs the application; whichever is later.
Conversion
- The Conversion option allow you to convert your term life insurance policy into permanent (e.g., whole life or universal life) insurance policy without providing evidence of insurability or undergoing new underwriting. Transitions from term to permanent coverage without having to do a new medical exam.
- This option is considered when an individual has ongoing health issues or may be unable to qualify for a new policy.
- An Insured Employee and Dependent(s) may convert Group Voluntary Life Insurance coverage, without evidence of insurability, to an Individual Life Insurance policy during the 31 day period following termination of employment.
It's essential for policyholders to consider the options available to you and request conversion or portability timely, within 30 days of your benefits termination. You will submit the request for conversion or portability directly to the insurance carrier and will set up direct payment for your new individual policy.
INCOME PROTECTION

Member Services | (833) 310-8260 | www.SecurianFinancial.com
Long-Term Disability
This employer-paid coverage pays a monthly benefit if you have a covered illness or injury and you can't work for a few months - or even longer! You're generally considered disabled if you're unable to do important parts of your job - and your income suffers as a result. This benefit is provided to you at no cost!
- Elimination Period- Benefits begin on the 90th day of an injury or illness.
- Benefit Duration - Payments may last up to Social Security Normal Retirement Age (SSNRA) (You must be sick or disabled for the duration of the waiting period before you can receive a benefit payment).
- Coverage Amount - Covers 60% of your monthly income, up to a maximum benefit of $5,000 per month.
- 3/12 Pre-existing Condition: If you have a medical condition that begins before your coverage takes effect, and you receive treatment for this condition within the three months leading up to your coverage start date, you may not be eligible for benefits for that condition until you have been covered by the plan for 12 months.
What does this mean to you?
- If you are still unable to work after your Short Term benefit expires, you will have the opportunity to receive a Long Term Disability cash benefit. Starting on the 90th day you are out of work due to an illness or injury, you will receive 60% of your monthly salary to a max of $5,000. You are able to receive these benefits for as long as you remain disabled or reach Social Security Normal Retirement Age (SSNRA).
REIMBURSEMENT

Member Services | (800) 303-9744 | app.pasito.ai/cedarparktexas
Voluntary Accident Insurance
A serious injury can cost you a lot of money – not only in medical bills but in things like income from lost work hours. Accident insurance is a robust shield against the unpredictable, safeguarding you against the financial fallout of unforeseen injuries. It pays a set benefit amount based on the type of injury you have and the type of treatment you need, ensuring that whether you face minor bruises or major medical emergencies, you're covered. Here's what accident insurance typically covers:
- Comprehensive Coverage: From fractures and dislocations to burns and concussions, accident insurance has you covered for a wide range of injuries.
- Medical Expenses: It helps offset expenses related to ambulance rides, hospital admissions, surgeries, therapy, and other necessary treatments.
- Income Protection: Should an injury result in lost work hours, accident insurance provides a financial safety net to help bridge the gap until you're back on your feet.
- Wellness Benefit: Receive $50 per year if you complete an approved wellness exam.
With accident insurance in your corner, you can face life's uncertainties with confidence, knowing that you're financially protected against the unexpected. However, it's important to note that accident insurance typically excludes coverage for routine check-ups or hospitalization due to illness. Additionally, injuries sustained prior to purchasing the accident insurance plan are not covered. For a detailed breakdown of benefits and coverage, refer to the plan summary provided below.
Voluntary Critical Illness Insurance
Facing a critical illness can bring not only physical strain but also financial burdens due to medical expenses and potential loss of income. Critical illness insurance serves as a robust safety net in such challenging times, offering financial protection against the unforeseen. In the event of a critical illness diagnosis, this insurance provides a lump-sum payment to the insured individual, enabling them to cover various expenses, including medical treatments, mortgage payments, and daily living expenses. Here's what critical illness insurance typically covers:
- Coverage for Various Conditions: Critical illness insurance typically covers a wide range of serious medical conditions, including cancer, heart attacks, strokes, organ transplants, and more. Visit your plan summary below to learn how different illnesses are covered.
- Financial Assistance: The policy provides a lump-sum payment upon diagnosis of a covered critical illness, allowing individuals to use the funds as needed for medical expenses, household bills, or other financial obligations.
- Flexibility and Peace of Mind: With critical illness insurance, employees gain peace of mind knowing they have financial protection in place, regardless of the specific illness they may face. This flexibility ensures that they can focus on their health and well-being without worrying about the financial consequences of a critical illness.
While critical illness insurance provides invaluable protection against serious medical conditions, it's essential to note that the plan typically excludes pre-existing conditions diagnosed before the policy's effective date, as well as certain illnesses not specified in the plan. Additionally, routine check-ups and hospitalization due to non-critical illnesses are typically not covered. For a comprehensive understanding of the benefits and limitations of your specific plan, be sure to review the plan summary provided below.
There are different plans available to provide coverage for you, your spouse and dependent children. Children under 25 are covered at no additional cost at 50% of employee's benefit
- Guaranteed Issue Coverage - Up to $40,000
- Maximum Coverage - $50,000
- Health Screening Benefit - $50/calendar year
Covered Illnesses Include (not limited to)
- Heart Attack
- Stroke
- Kidney Failure
- Organ Transplant
- Cancer
Hospital Indemnity Insurance
Even if you have medical insurance, a trip to the hospital can leave you with significant unexpected expenses. Hospital indemnity insurance is a valuable addition to your benefits package, providing financial protection in the event of hospitalization due to illness or injury. This insurance offers a fixed daily benefit amount for each day you're hospitalized, helping offset expenses not covered by your primary health insurance, such as deductibles, copayments, and other out-of-pocket costs. It serves as a financial safety net, ensuring that you can focus on your recovery without worrying about the financial impact of a hospital stay. Here's what hospital indemnity insurance typically includes:
- Daily Hospitalization Benefit: You receive a fixed cash benefit for each day spent in the hospital, providing financial assistance to cover various expenses incurred during your stay. You can receive benefits when you’re admitted to the hospital for a covered accident, illness, or childbirth. See the full list in the plan summary below.
- Flexibility in Use: The benefit can be used at your discretion to cover costs like deductibles, copayments, transportation, and even household bills while you're unable to work.
While hospital indemnity insurance offers valuable financial support during hospitalization, it's important to note that it typically excludes coverage for pre-existing conditions and certain elective procedures. Additionally, benefits may not be payable for hospital stays due to specific causes, so be sure to review the plan summary below for more information on coverage details and limitations. Your understanding of the plan specifics will empower you to make informed decisions about your healthcare coverage.
Click the link below to visit the Hartford website for more information on your Accident, Critical Illness, and Hospital Indemnity Plans!

EMPLOYEE ASSISTANCE PROGRAM (EAP)

Member Services | (866) 212-6096 | www.Neely.com
Find professional support when you need it for challenging life events.
- Through your Neely Employee Assistance Program, you have access to many helpful services that address personal life challenges and improve workplace productivity and performance. We are proud to offer our Employee Assistance Program (EAP) in partnership with Neely.
- You and your family members can use EAP services — no copays or deductibles needed.
Included Services:
- Guidance Consultants: When going through a difficult time, having someone to talk to can make a big difference in your state of mind.
- GuidanceResources® Online: Whenever you need guidance on important life matters, visit GuidanceResources.com or download the GuidanceNow mobile app. You’ll find help on relationships, work, school, children, legal, financial concerns and more.
- Financial Services: Everyone needs a bit of financial advice now and then. With EmployeeConnect Plus, you can speak with a ComPsych® financial expert to discuss managing personal financial challenges, credit card and debt management, budgeting, tax questions, and more.
- Legal Services: You can easily feel overwhelmed when faced with legal issues. Fortunately, help is just a phone call away. EmployeeConnect Plus gives you access to a ComPsych® staff attorney.
- Work-life Services: When you need help resolving issues at home or work, EmployeeConnect Plus is here for you. Work-life specialists will research your question and will send you information based on your needs.
Reach Out
Don’t be afraid to reach out for help. Your health records are kept private from your employer, as required by law.
- Call: (866) 212-6096
- Online: Home - Neely EAP
- App:


MENTAL HEALTH: ADDITIONAL RESOURCES
Call 911 if you or someone you know is in immediate danger or go to the nearest emergency room.
988 Suicide & Crisis Lifeline
- Dial 988 to be connected with 24/7/365 emotional support.
- Free, confidential crisis counseling, including appropriate follow-up services, is available no matter where you live in the United States.
War Vet Call Center
- Veterans and their families call 877-WAR-VETS (877-927-8387) to talk about their military experience and/or readjustment to civilian life.
MEDICARE ELIGIBILITY
Medicare eligibility is a critical aspect of healthcare planning, particularly for individuals nearing age 65 or those with qualifying disabilities. Here are the key points to keep in mind:
- **Age 65 or Qualifying Disability**: Most individuals become eligible for Medicare at age 65, while those with certain disabilities or medical conditions may qualify earlier.
- **Comprehensive Coverage**: Medicare provides coverage for hospital stays, medical services, prescription drugs, and preventive care, offering essential healthcare benefits.
- **Enrollment Periods**: It's important to understand the various enrollment periods for Medicare, including the initial enrollment period, special enrollment periods, and annual open enrollment periods for making changes to coverage.
- **Supplemental Coverage Options**: Many individuals choose to supplement their Medicare coverage with additional plans, such as Medicare Advantage (Part C) or Medicare Supplement Insurance (Medigap), to enhance benefits and fill gaps in coverage.
As you navigate your benefit elections, be sure to consider your Medicare eligibility and options alongside your employer-provided benefits. Understanding your Medicare coverage can help ensure comprehensive healthcare coverage that meets your needs as you transition into retirement.
RESOURCES
GLOSSARY
- Premium: The amount paid for insurance coverage deducted from your paycheck on a per-pay-period basis.
- Deductible: The amount you must pay out of pocket for covered services before your insurance plan starts to pay.
- Copayment (Copay): A fixed amount you pay for covered services at the time of service, usually for doctor visits or prescription drugs.
- Coinsurance: The percentage of costs you pay for covered services after you've met your deductible.
- Out-of-Pocket Maximum: The maximum amount you'll have to pay for covered services in a plan year, after which your insurance plan pays 100% of covered costs.
- Network: The group of doctors, hospitals, and other healthcare providers contracted with an insurance company to provide services at discounted rates to plan members.
- Preventive Care: Healthcare services aimed at preventing illness or detecting health conditions early when treatment is most effective, often covered at no cost under insurance plans.
- Benefit: The healthcare services or items covered by an insurance plan.
- Preauthorization: The process of obtaining approval from your insurance company before receiving certain medical services or treatments.
- In-Network: Healthcare providers or facilities that have contracted with your insurance company to provide services at lower costs to plan members.
- Exclusion: Specific healthcare services or conditions that are not covered by an insurance plan.
- Lifetime Maximum: The maximum amount of money that an insurance plan will pay for covered services over the entire life of the policy.
- Grace Period: A specified period after the premium due date during which coverage remains in force even though the premium has not been paid.
- Coordination of Benefits (COB): A process used when an individual is covered under more than one health insurance plan to determine which plan pays first and how much each plan will pay.
- Explanation of Benefits (EOB): A statement sent by the insurance company to the insured individual explaining what medical treatments and/or services were paid for on their behalf.
Why go to an In-network provider?
- Going to an in-network provider means choosing a healthcare professional or facility that has a contract with your health insurance plan. In-network providers have agreed to offer their services at negotiated rates, which are often lower than what you would pay for out-of-network care. By visiting an in-network provider, you can take advantage of your health insurance plan's benefits, which may include lower copayments, coinsurance, and reduced out-of-pocket expenses.
Why should I go for my annual well checkup?
- Annual well checkups are essential for maintaining good health and preventing potential health issues. These visits allow your doctor to assess your overall health, monitor any chronic conditions you might have, and detect early signs of potential health problems. Regular checkups help identify health concerns before they become serious, ensuring timely intervention and a better chance for successful treatment.
What is the difference between generic and brand name drugs?
- Generic drugs are identical or bioequivalent to brand-name drugs in terms of active ingredients, safety, strength, dosage form, and intended use. The main difference is that generic drugs are usually more affordable because they don't have the research and development costs associated with brand-name drugs. The U.S. Food and Drug Administration (FDA) ensures that generic drugs meet the same rigorous standards for quality, safety, and effectiveness as their brand-name counterparts.
How do discount cards work on RX?
- Prescription discount cards provide discounts on medications at participating pharmacies. These cards are often available for free or at a low cost and can be used by individuals without insurance or those with high copayments. When you present the discount card at the pharmacy, it reduces the price of the medication, potentially leading to significant cost savings.
What happens if I go out of network?
- If you go out of network for healthcare services, it means you're seeing a provider or using a facility that doesn't have a contract with your health insurance plan. Out-of-network care typically results in higher out-of-pocket costs, including higher copayments, coinsurance, and potentially higher deductibles. Some health insurance plans may not cover out-of-network care at all, except in emergencies.
What is a SBC (Summary of Benefits and Coverage)?
- A Summary of Benefits and Coverage (SBC) is a document provided by health insurance companies to help individuals understand their health plan's key features and coverage details. It provides a summary of the plan's benefits, costs, coverage limits, and examples of common medical scenarios to help individuals compare different health insurance options and make informed decisions.
What is an EOB (Explanation of Benefits)?
- An Explanation of Benefits (EOB) is a statement sent by the health insurance company to the policyholder after a healthcare claim has been processed. The EOB provides a detailed explanation of the services provided, the amount billed by the healthcare provider, the amount covered by the insurance, and any remaining balance that the insured may be responsible for paying.
What should I ask my doctor?
- When visiting your doctor, consider asking questions related to your health condition, treatment options, medications, potential side effects, and any lifestyle changes you should make. You can also inquire about preventive measures, recommended screenings, and follow-up care. Don't hesitate to ask for clarification if there's anything you don't understand.
What is preventive care?
- Preventive care refers to healthcare services aimed at preventing or detecting health issues before they become more severe or chronic. Examples of preventive care include vaccinations, screenings (e.g., mammograms, colonoscopies), regular checkups, counseling on healthy behaviors, and interventions to manage risk factors.
Where can I get my ID card?
- You can typically get your health insurance ID card from your insurance provider. Many insurers offer electronic versions of the ID card through their mobile apps or member portals. Alternatively, you can request a physical ID card to be mailed to you.
Who do I contact if I have a QLE (Qualifying Life Event)?
- If you experience a Qualifying Life Event (QLE), such as marriage, birth/adoption of a child, divorce, loss of other health coverage, or a change in household income, you should contact your employer's HR department or your health insurance provider promptly. They can guide you through the process of updating your health insurance coverage or enrolling in a new plan if necessary.